
OFFICIAL PUBLICATION OF THE COMMUNITY BANKERS ASSOCIATION OF KANSAS

2026 Pub. 7 Issue 5

Record Municipal Issuance Infrastructure

Necessity or Credit Warning Sign?

Municipal issuance is on pace for a third consecutive record year, with dealers forecasting roughly $600 billion of new supply in 2026 after 2025’s record of about $580 billion. For municipal bondholders, the question is not whether the market can absorb the supply — so far, it has. Rather, the question is whether the debt being issued to fund this infrastructure wave is being taken on prudently at the issuer level, or whether it is quietly eroding the credit cushion that underpins the municipal market’s safe reputation built on extremely low default rates and the security of taxing power and essential services.

Why Debt Levels Are Rising

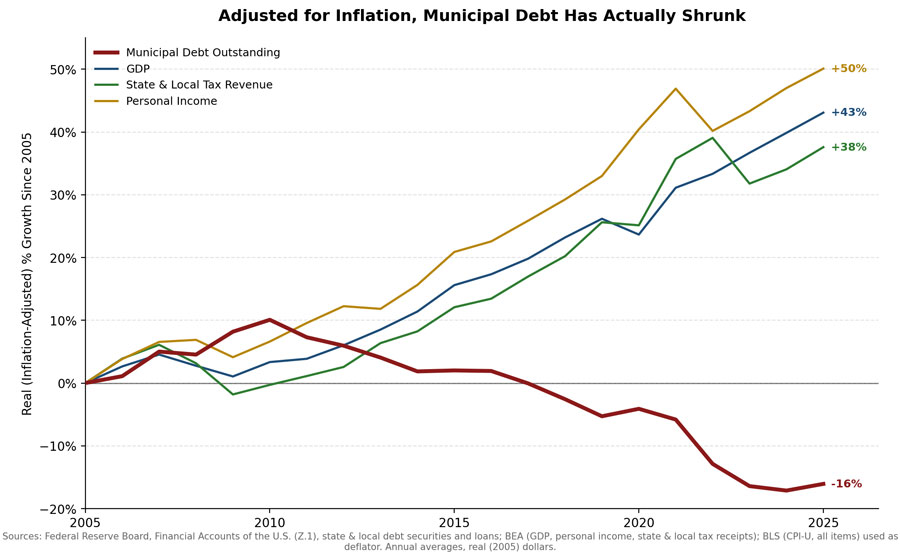
As demonstrated in the chart below, aggregate municipal debt outstanding has shrunk by roughly 16% in inflation-adjusted terms since 2005, even as GDP, state and local tax revenue, and personal income have grown by 38% or more.
However, several forces are converging to push both debt levels and debt service costs higher. First, aging infrastructure needs to be replaced. The American Society of Civil Engineers’ latest report card shows the national infrastructure funding gap widening to $3.7 trillion, up from $2.6 trillion four years earlier. Second, demand for additional infrastructure is adding to that burden. For example, public power utilities are raising capital to meet AI-driven data center load, population migration necessitates more capital investment in some areas like Texas and Florida, and physical mitigants to manage climate risk are increasingly important.

Meanwhile, the federal support that has let issuers avoid debt in recent years is fading. Pandemic-era stimulus funding for pay-as-you-go capital projects has run out, leading to a larger proportion of capital projects needing to be funded with bond proceeds. Timing compounds the problem as both construction costs and borrowing rates are elevated. Many issuers delayed projects as interest rates rose, expecting a pullback that never fully came, and are now financing those same plans at rates well above what they could have locked in a few years earlier. At the same time, inflation has driven up construction costs rapidly, making these projects much more expensive.

That said, higher debt isn’t inherently a problem for every issuer. Many municipalities are currently well-positioned with high reserves, strong revenue sources and conservative budgeting practices, but also have legitimate needs to increase leverage. However, risk arises from debt and associated costs outpacing an issuer’s capacity to manage them, particularly if additional capital needs keep surfacing while revenue and reserve growth slow or reverse. The following are some credit indicators to help manage that risk.

Credit Indicators to Monitor

  • Debt-load metrics. Materially rising per-capita debt and debt-to-assessed ratios signal a tax base being asked to support more debt without a commensurate increase in capacity. Overlapping debt is also enlightening, as a taxpayer within overlapping jurisdictions can carry a much heavier load than any single issuer’s balance sheet would suggest.
  • Reserve erosion relative to debt service. Watch the general fund balance relative to annual debt service, and whether the issuer is drawing down reserves to cover recurring operating costs rather than one-time items.
  • Taxpayer concentration. If a small number of taxpayers account for a large share of assessed value, the credit is more fragile than the aggregate numbers imply. The departure or downsizing of a large employer or taxpayer can materially affect the tax base.
  • Tax collection rate. A decreasing collection rate is an important distress signal — it reflects real-time taxpayer stress and local administrative capacity to enforce collections.
  • Disclosure and administrative behavior. Late or missing continuing disclosure filings, delayed audits or qualified/adverse audit opinions tend to correlate with weaker management generally, and non-compliance itself can raise an issuer’s cost of funds independent of the underlying credit.
  • Low or falling coverage ratio on revenue bonds. An issuer that repeatedly issues new parity debt against the same revenue stream dilutes its debt coverage. A low coverage ratio leaves less cushion to absorb a revenue shortfall before payment is at risk.

The Bottom Line

Infrastructure investment is genuinely needed, and the municipal bond market remains a proven avenue for funding it, with historically solid credit quality. The recent pickup in issuance appears to be a normalization of debt levels, but investors should stay vigilant. Debt raised against durable, well-supported revenue is different than debt raised against optimistic assumptions or by issuers already in a fragile financial state. Instead of evaluating a debt increase in isolation, investors should comprehensively analyze the issuer’s ability to sustainably carry the additional debt. The Baker Group’s credit analysts are available to help you apply this framework to specific issuers in your portfolio.

Dana Sparkman, CFA, is executive vice president-municipal analyst in The Baker Group’s Financial Strategies Group. She manages a municipal credit database covering more than 300,000 municipal bonds, providing clients with specific credit metrics essential for assessing municipal credit. Dana earned a bachelor’s degree in finance from the University of Central Oklahoma and the Chartered Financial Analyst designation. Contact her at The Baker Group by calling (800) 937-2257.
Record Municipal Issuance Infrastructure

Necessity or Credit Warning Sign?

Municipal issuance is on pace for a third consecutive record year, with dealers forecasting roughly $600 billion of new supply in 2026 after 2025’s record of about $580 billion. For municipal bondholders, the question is not whether the market can absorb the supply — so far, it has. Rather, the question is whether the debt being issued to fund this infrastructure wave is being taken on prudently at the issuer level, or whether it is quietly eroding the credit cushion that underpins the municipal market’s safe reputation built on extremely low default rates and the security of taxing power and essential services.

Why Debt Levels Are Rising

As demonstrated in the chart below, aggregate municipal debt outstanding has shrunk by roughly 16% in inflation-adjusted terms since 2005, even as GDP, state and local tax revenue, and personal income have grown by 38% or more.

However, several forces are converging to push both debt levels and debt service costs higher. First, aging infrastructure needs to be replaced. The American Society of Civil Engineers’ latest report card shows the national infrastructure funding gap widening to $3.7 trillion, up from $2.6 trillion four years earlier. Second, demand for additional infrastructure is adding to that burden. For example, public power utilities are raising capital to meet AI-driven data center load, population migration necessitates more capital investment in some areas like Texas and Florida, and physical mitigants to manage climate risk are increasingly important.

Meanwhile, the federal support that has let issuers avoid debt in recent years is fading. Pandemic-era stimulus funding for pay-as-you-go capital projects has run out, leading to a larger proportion of capital projects needing to be funded with bond proceeds. Timing compounds the problem as both construction costs and borrowing rates are elevated. Many issuers delayed projects as interest rates rose, expecting a pullback that never fully came, and are now financing those same plans at rates well above what they could have locked in a few years earlier. At the same time, inflation has driven up construction costs rapidly, making these projects much more expensive.

That said, higher debt isn’t inherently a problem for every issuer. Many municipalities are currently well-positioned with high reserves, strong revenue sources and conservative budgeting practices, but also have legitimate needs to increase leverage. However, risk arises from debt and associated costs outpacing an issuer’s capacity to manage them, particularly if additional capital needs keep surfacing while revenue and reserve growth slow or reverse. The following are some credit indicators to help manage that risk.

Credit Indicators to Monitor

  • Debt-load metrics. Materially rising per-capita debt and debt-to-assessed ratios signal a tax base being asked to support more debt without a commensurate increase in capacity. Overlapping debt is also enlightening, as a taxpayer within overlapping jurisdictions can carry a much heavier load than any single issuer’s balance sheet would suggest.
  • Reserve erosion relative to debt service. Watch the general fund balance relative to annual debt service, and whether the issuer is drawing down reserves to cover recurring operating costs rather than one-time items.
  • Taxpayer concentration. If a small number of taxpayers account for a large share of assessed value, the credit is more fragile than the aggregate numbers imply. The departure or downsizing of a large employer or taxpayer can materially affect the tax base.
  • Tax collection rate. A decreasing collection rate is an important distress signal — it reflects real-time taxpayer stress and local administrative capacity to enforce collections.
  • Disclosure and administrative behavior. Late or missing continuing disclosure filings, delayed audits or qualified/adverse audit opinions tend to correlate with weaker management generally, and non-compliance itself can raise an issuer’s cost of funds independent of the underlying credit.
  • Low or falling coverage ratio on revenue bonds. An issuer that repeatedly issues new parity debt against the same revenue stream dilutes its debt coverage. A low coverage ratio leaves less cushion to absorb a revenue shortfall before payment is at risk.

The Bottom Line

Infrastructure investment is genuinely needed, and the municipal bond market remains a proven avenue for funding it, with historically solid credit quality. The recent pickup in issuance appears to be a normalization of debt levels, but investors should stay vigilant. Debt raised against durable, well-supported revenue is different than debt raised against optimistic assumptions or by issuers already in a fragile financial state. Instead of evaluating a debt increase in isolation, investors should comprehensively analyze the issuer’s ability to sustainably carry the additional debt. The Baker Group’s credit analysts are available to help you apply this framework to specific issuers in your portfolio.

Dana Sparkman, CFA, is executive vice president-municipal analyst in The Baker Group’s Financial Strategies Group. She manages a municipal credit database covering more than 300,000 municipal bonds, providing clients with specific credit metrics essential for assessing municipal credit. Dana earned a bachelor’s degree in finance from the University of Central Oklahoma and the Chartered Financial Analyst designation. Contact her at The Baker Group by calling (800) 937-2257.
Sign Up to Receive this Publication in your inbox​